
Article · AI in Banking
Mobile Banking 2026 – Benchmarks, Evidence, and Execution
By 2026, mobile banking will have become the operating system of retail banks. Benchmarks from McKinsey, Bain, BCG, and Euromoney confirm that leaders achieve 30–50% lower service costs, 2–3× productivity gains, and…
Dato Arif Siddiqui · 8 Jan 2026
By 2026, mobile banking will have become the operating system of retail banks. Benchmarks from McKinsey, Bain, BCG, and Euromoney confirm that leaders achieve 30–50% lower service costs, 2–3× productivity gains, and higher ROE. This paper combines published benchmarks with disclosed bank metrics to show how execution—not experimentation—defines winners.
Benchmark Evidence
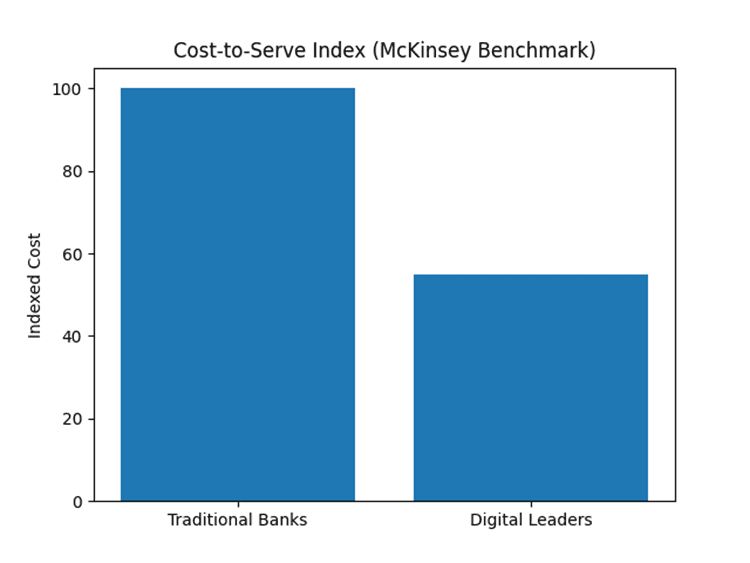
1. McKinsey – Digital Cost Efficiency
McKinsey’s Global Banking Annual Review shows digitally mature banks operate with 30–50% lower cost-to-serve due to mobile self-service, AI automation, and reduced branch dependency. Source: https://www.mckinsey.com/industries/financial-services/our-insights/global-banking-annual-review
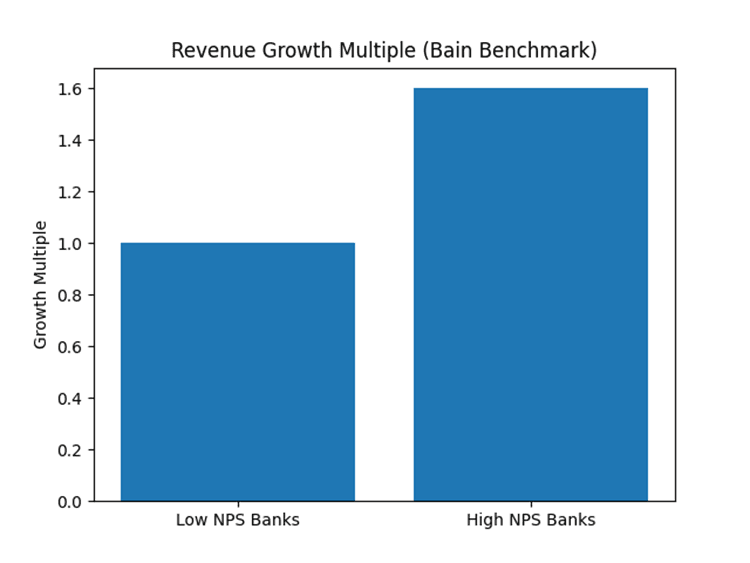
2. Bain – CX, NPS, and Growth
Bain research links high mobile CX and NPS with materially faster revenue growth. Top-quartile digital banks grow up to 1.6× faster than peers. Source: https://www.bain.com/insights/topics/customer-experience/
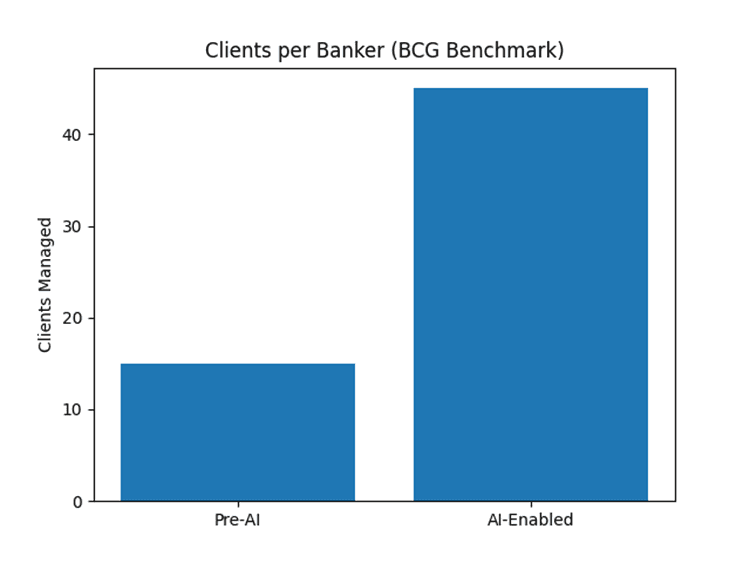
3. BCG – Productivity Impact of AI
BCG benchmarks show AI-enabled mobile workflows expand banker capacity from ~15 clients to 40–50 clients per banker. Source: https://www.bcg.com/industries/financial-institutions
Bank Case Studies — What 2026 Looks Like (based on 2025 direction)
1) Chase (JPMorgan Chase): ‘Mobile-first at scale.’
The disclosed scale is unmatched in the U.S. consumer market. JPMorgan Chase reported ~59.0 million active mobile customers and ~72.5 million active digital customers (logged in in the last 90 days) as of March 31, 2025. That scale matters because it changes the unit economics of service. When disputes, card controls, alerts, servicing, and sales journeys shift to mobile, branch, and call-center load reduces, and product-per-customer rises. CX impact (what changes customers actually feel): • Faster “self-serve” resolution for routine tasks. • More proactive alerts and embedded financial health features. • Higher stickiness from one-app consolidation (banking + payments + wealth). ROI impact (how it shows up in numbers): JPMC discloses mobile and digital active counts inside its core operating metrics, and highlights payments volume growth alongside customer digital scale. The implicit ROI is lower cost-to-serve plus higher digital engagement per customer. 2026 implication: Chase will keep pushing mobile as the default service layer, with more proactive tools and instant-rail experiences.
2) Bank of America: ‘AI + digital interactions as the growth engine.’
Bank of America’s 2025 disclosures show digital ata massive scale: 58+ million verified digital clients and 26 billion digital interactions in 2024, up 12% year-over-year. Erica remains a key CX lever: 20 million clients use Erica, and interactions exceeded 2.5 billion (as of Feb 2025). Later disclosures cite >3 billion Erica interactions, and that it performs work equivalent to thousands of employees. CX impact: • Proactive alerts and guided actions reduce customer effort. • AI assistant reduces navigation friction and increases completion rates. • Always-on help improves perceived responsiveness. ROI impact: Reuters reported BofA’s internal productivity impact: AI helped bankers manage more clients (coverage rising from 15 to 50 clients per banker) and supported revenue uplift through better preparation and personalization. This is a direct “CX to ROI” bridge: better tools → faster service → more capacity → more revenue per banker. 2026 implication: expect further expansion of banker copilots and deeper Erica workflows (disputes, card servicing, onboarding support).
3) DBS: ‘Mobile as a platform, measured by efficiency and ROE.’
DBS is often used as the benchmark for a bank that treated digital as the operating model, not a channel. In its 2024 annual reporting, DBS disclosed a cost-income ratio of ~40% and a return on equity (ROE) of ~18%. Independent coverage (e.g., Euromoney recognition) also notes the same efficiency and ROE profile. CX impact: • Consistent mobile journeys across daily banking + wealth. • Strong satisfaction and retention emphasis (explicitly referenced in DBS reporting narratives and award citations). ROI impact: Maintaining ~40% cost-income while continuing to invest in technology indicates strong digital ROI: growth without proportional cost growth. 2026 implication: DBS will keep extending platform capabilities (wealth, lending, lifestyle integrations) and use AI to industrialize personalization.
4) ICICI Bank: ‘Mobile + UPI scale to drive migration and cross-sell.’
ICICI discloses that iMobile Pay has more than 30 million users, and that total transaction value through the app was close to ₹11,000 billion in fiscal 2024. That is a concrete, bank-disclosed adoption + usage measure. CX impact: • Payments-led entry point (UPI and QR) increases daily frequency. • Service and product journeys become “one tap away” from payments. ROI impact: Transaction migration to mobile reduces unit processing cost versus branch/call. High app transaction value supports fee and float economics, and creates a better cross-sell surface for cards, deposits, and loans. 2026 implication: deeper integration of payments + credit + service workflows inside one app, with faster onboarding and smarter fraud controls.
5) HSBC: ‘Mobile experience refresh + NPS focus + resilience.’
HSBC’s group reporting emphasizes Net Promoter Score (NPS) as a core customer measure, and its annual reporting includes commentary about improving customer satisfaction performance across markets. In Hong Kong, external reporting in 2025 stated HSBC’s active mobile user base almost doubled between 2020 and 2024, against a customer base of about 6.2 million in Hong Kong. CX impact: • App redesign and money-management features aim to close the gap versus digital-first challengers. • NPS-driven feedback loops push faster fixes and better journeys. • Operational resilience becomes part of CX: fewer outages, faster recovery. ROI impact: HSBC’s transformation/simplification agenda targets efficiency and returns; in 2026, mobile becomes a primary lever to reduce service costs and deepen relationships in core hubs (HK, UK). 2026 implication: unified mobile UX, better cross-border value proposition, and heavy focus on reliability.
What to Watch in 2026 (based on 2025 direction)
1) Mobile becomes the primary ‘service operating system’.
2) AI shifts from chat to workflow automation (disputes, onboarding, servicing).
3) Payment rails (instant + wallet) become the mobile engagement engine.
4) CX metrics (NPS, engagement) tie directly to banker productivity and revenue.
5) Reliability (outages, fraud, scams) becomes a top mobile differentiator.
Key Sources
- JPMorgan Chase Corp Q1 2025 (active digital + active mobile customers): https://www.jpmorganchase.com/ir/quarterly-earnings
- Chase study (app users, feature engagement): https://media.chase.com/news/consumers-are-using-banking-apps-for-more-than-transactions-new-chase-study-finds
- Bank of America 2025 press release (digital interactions, verified digital clients, Erica usage): https://newsroom.bankofamerica.com/content/newsroom/press-releases/2025/02/digital-interactions-by-bofa-clients-surge-to-over-26-billion--u.html
- Bank of America Reuters (AI productivity + revenue impact): https://www.reuters.com/business/finance/bofa-says-ai-is-boosting-bankers-productivity-revenue-2025-11-17/
- DBS Annual Report 2024 (cost-income, ROE): https://www.dbs.com/investors/annual-report
- DBS Euromoney 2025 page (cost/income, ROE mention): https://www.dbs.com/about-us/who-we-are/awards-accolades/a-world-first/euromoney-worlds-best-bank-2025
- ICICI iMobile Pay users and FY24 transaction value: https://www.icici.bank.in/ms/simplify/bank-at-a-glance.html
- HSBC Annual Report 2024 (NPS / customer measures): https://www.hsbc.com/investors/results-and-announcements/all-reporting
- HSBC Hong Kong mobile user base trend (SCMP report): https://www.scmp.com/business/banking-finance/article/3309436/hsbc-revamps-hong-kong-mobile-app-boost-user-experience-banking-convenience